The 4-Bucket System That Lets You Finally Stop Worrying About Money
Even if you've never had a plan, don't earn a fortune, and have no one you trust to ask. A brutally simple, 81-page field guide, plus ten tools that make you actually do it, for turning any income into lifelong financial safety.
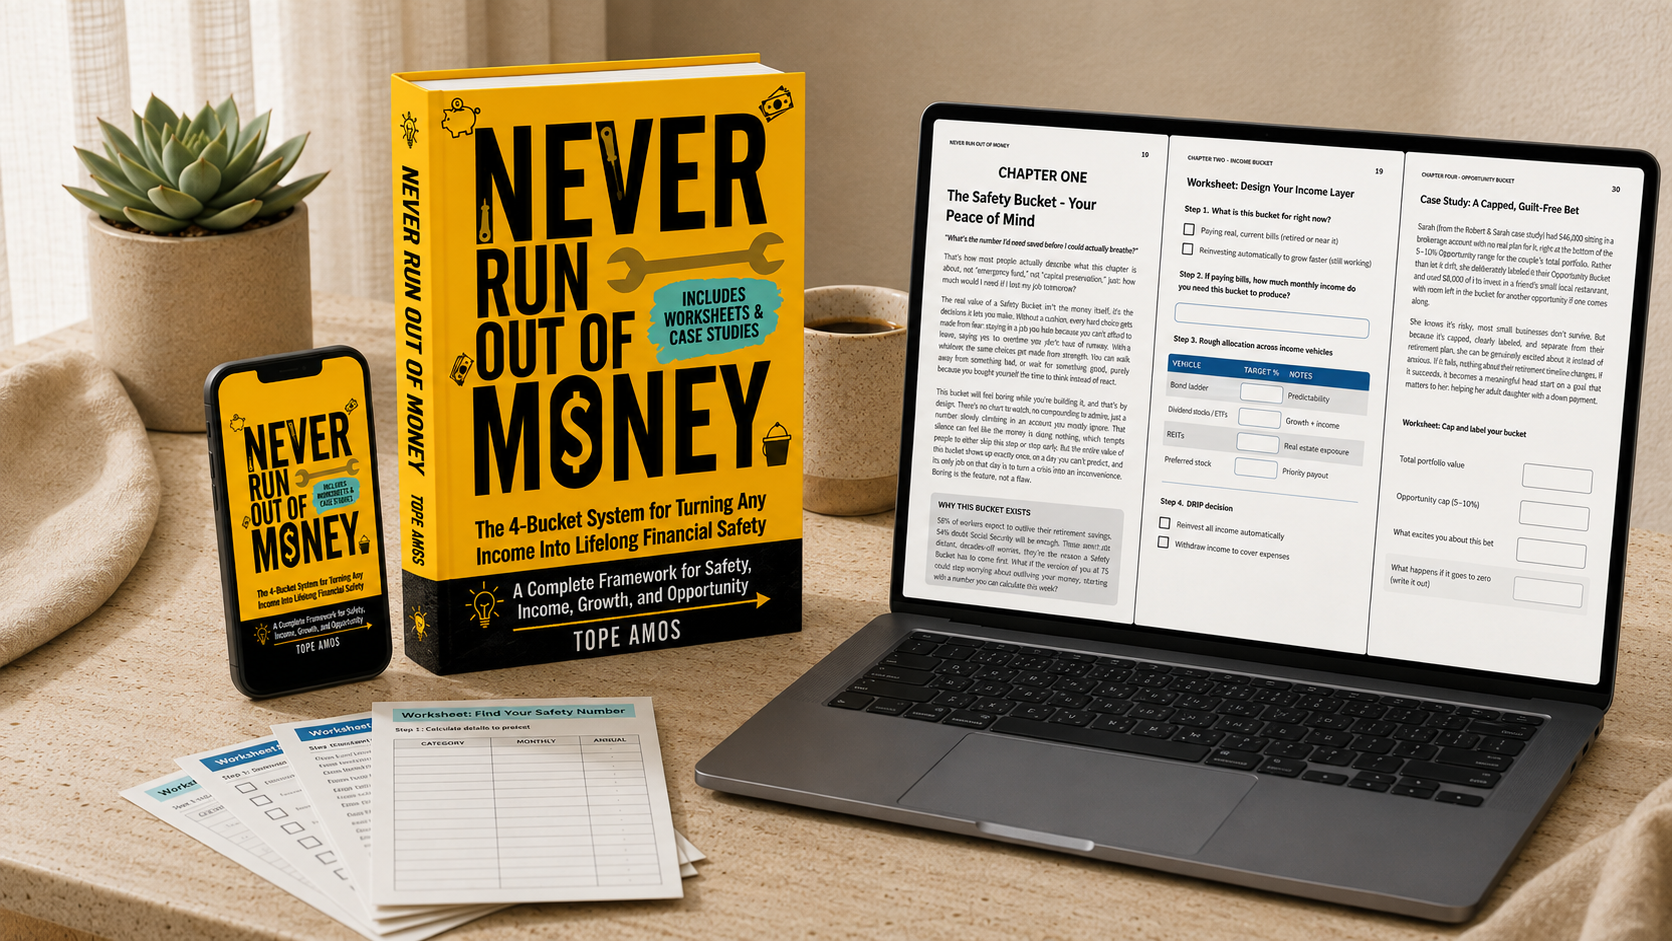
Instant digital delivery • 10 implementation tools included
OR
Why "just save and invest" has failed you.
And the 4-Buckets Money System that fix it
You did the things they told you to do.
You made a budget. You cut the subscriptions. You told yourself you'd "invest once things settle down."
And still, every time you get a little ahead, prices go up and you're behind again. Something always sets you back.
You're not imagining it. In the National Foundation for Credit Counseling's 2025 Financial Literacy and Preparedness Survey (conducted by The Harris Poll among 2,010 U.S. adults), 53% of Americans said that no matter how hard they try to get ahead, something always comes up to set them back, and 48% said they feel like they're constantly treading water, where any unexpected expense could pull them under.
Here's what almost nobody says out loud: the fear isn't really about money. It's about safety.
It has to be safe.
It has to grow.
It has to be available.
It has to generate income.
It has to fund opportunities.
No dollar can do all of that at once.
The fear isn't really about money. It's about safety.
You are not the only one lying awake.
In Allianz Life's 2025 Annual Retirement Study (an online survey of 1,000 Americans age 25+, conducted January, February 2025), 64% said they worry more about running out of money than they worry about death itself.
You've felt that. The tightness in the chest. The mental math at 2 a.m. The quiet dread that you'll do everything "right" and still end up a burden to the people you love.
You don't need another budgeting app. You need to feel safe. This book is about exactly how you get there.
64%
fear running out of money more than death.
53%
say something always sets them back.
48%
feel like they're constantly treading water.
You don't need another budgeting app. You need to feel safe.
This was built for people who have income, but don't have a system.
This is for you if…
You have some income but no system, money comes in, money goes out, and you genuinely can't tell if you're okay.
You want to reach financial independence and stop depending on a single paycheck.
You're afraid you'll outlive your savings, a fear you share with 58% of workers, who told Goldman Sachs Asset Management's 2025 Retirement Survey & Insights Report that they believe they'll outlive their retirement savings.
You're 5-10 years from retirement with a few scattered old 401(k)s, and you're terrified a downturn will hit right as you stop working.
You want your kids to grow up smarter about money than you did.
You're exhausted by conflicting advice and don't fully trust that advisors have your best interest at heart.
This is not for you if…
You want get-rich-quick schemes.
You want hot stock tips.
You want someone to manage your money for you without you ever understanding it.
You already have a written, layered plan that you follow through every market crash without flinching.
If that's you, keep your $19
Stop asking "Is this a good investment?" Start asking "Which bucket does this money belong in?"
Nearly every money mistake comes from money being in the wrong place for its job. The emergency fund gets gambled on a hot stock. The long-term money sits in cash, quietly losing to inflation. You freeze, because every single dollar is being asked to do everything at once.
The 4-Bucket System gives every dollar exactly one job.
Bucket | Its Job | Time Horizon | Risk Level |
Safety | Protect you | 0–3 years | Extremely low |
Income | Pay you | 3–10 years | Low–medium |
Growth | Build you | 10+ years | Medium–high |
Opportunity | Excite you | Variable | High–very high |
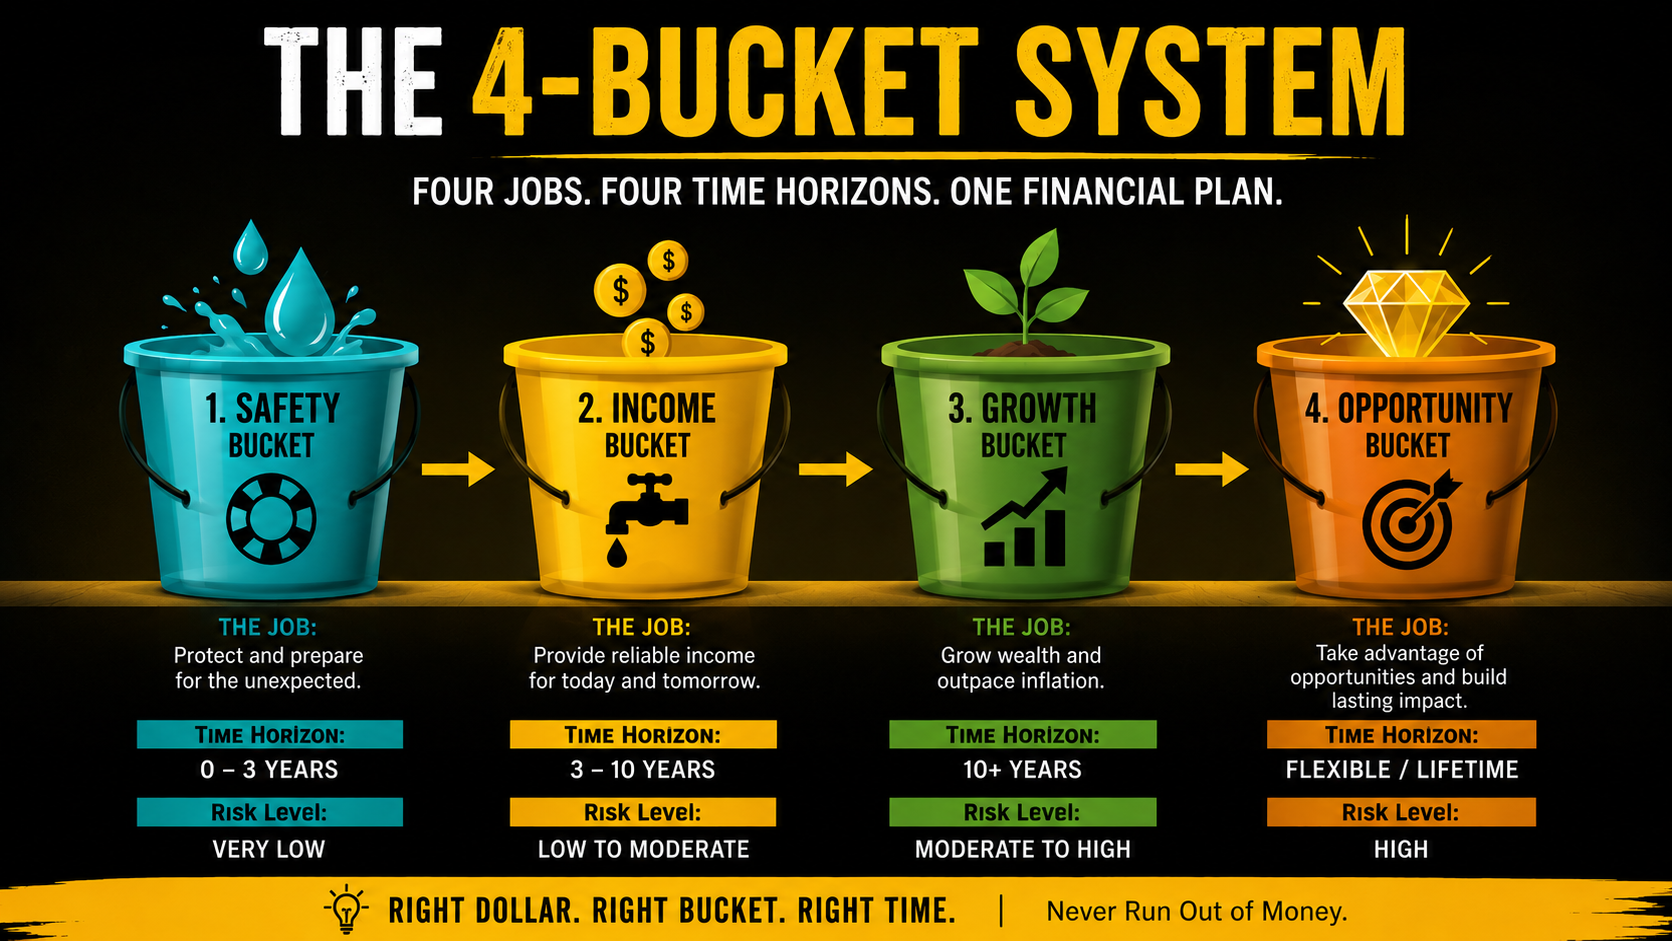
Every dollar gets one job.
A market crash stops being terrifying.
A tempting opportunity stops being a threat to your future.
You stop needing to predict everything.
A system the market can't touch, so you can finally breathe.
Instant digital delivery • 10 implementation tools included
OR
Why trust this book?
Because it doesn't ask you to.
Tope Amos isn't a guru promising secret returns. This is a system built entirely on publicly cited, named, and dated research, with a complete Sources & Notes page in the back so you can check every number yourself.
That's the credibility hook, and it's deliberate: every claim is sourced, every case study is labelled illustrative, and every worksheet is built so you verify it with your own numbers. You never have to take anyone's word for anything.
Every statistic is named and dated
No "studies show." Sources and notes run from page 70 to page 74, so you can go and read the original.
Every case study is labelled illustrative.
The people in the examples are composites used to show the arithmetic. They are never presented as clients or results.
Every worksheet lets you verify yourself.
You do the sum with your own numbers. If the conclusion doesn't hold for you, you'll see it immediately.
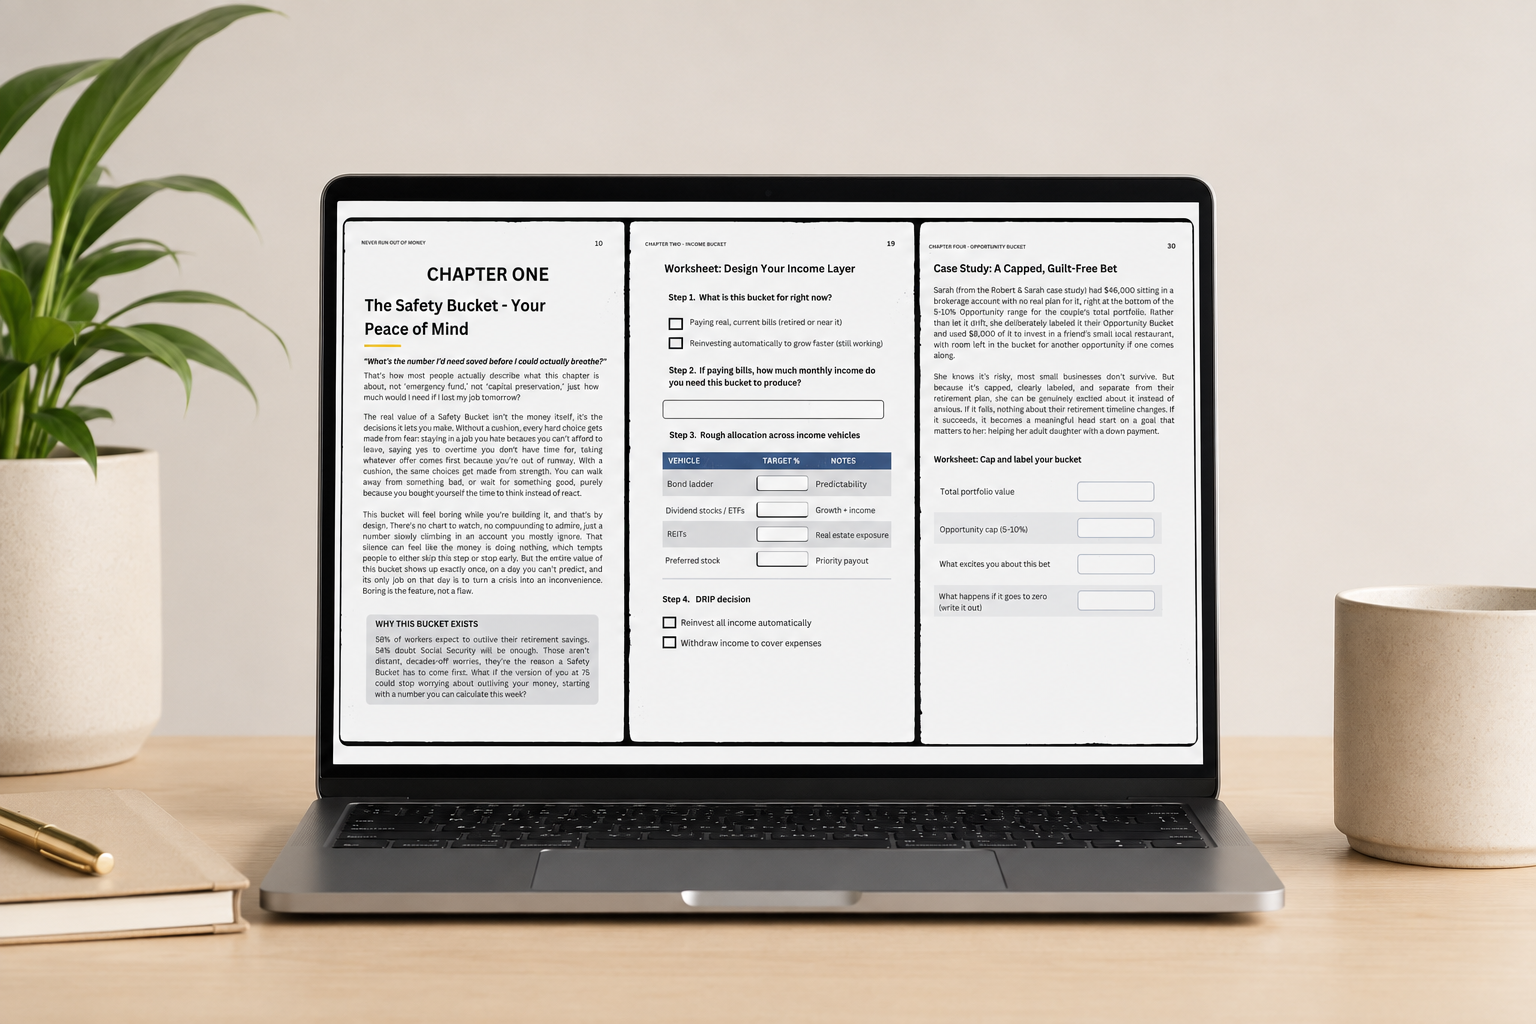
Five pages of references at the back.
A book that tells you not to trust financial advice on faith has to show its own working. Every figure quoted on this page appears there with its source and date.
A taste of what you'll find inside Never Run Out of Money
The one question to ask before anything else: "What's the number I'd need saved before I could actually breathe?," plus the one-line worksheet that hands you your Safety Number in about two minutes. (p. 14)
Why the old "3-6 months of expenses" rule quietly became dangerous, and the wider cushion you actually need now. (p. 11)
Where safety money really goes, in plain English, the real difference between an HYSA, a money-market fund, a CD, and a short-term T-bill. Finally, no jargon. (p. 13)
"Isn't holding a year of cash a waste? Won't inflation eat it?," the honest answers. (p. 12)
Case study: how Alex (earns $72,000, $3,100/mo essentials) landed on a $27,900 Safety Number, moved $9,000 sitting idle into an HYSA, and set a calm $450/month autotransfer. (p. 15)
Why "you don't have a budgeting problem, you have an income-timing problem," and what to do about it. (p. 16)
How the same dollar can do two completely different jobs: quietly reinvesting through a DRIP while you work, then becoming a paycheck the day you retire. (p. 17)
Annuities: "isn't that the thing insurance salespeople push?," the honest, no-commission take. (p. 18)
Case study: how Robert & Sarah built a $300,000 Income Bucket, a five-year bond ladder plus dividend index funds at a roughly 4% blended yield, throwing off about $12,000 a year, covering roughly a quarter of their essentials without ever touching the principal. (p. 20)
Why "you don't need to predict the market, you need a bucket the market can't touch for ten years." (p. 21)
The difference between volatility and risk that keeps calm investors calm, and panicky ones broke. (p. 21)
The compounding table that shows what steady, boring investing could become over 35 years, clearly labelled as an illustrative example, not a promise. (p. 24)
The one habit that removes the need to ever guess whether today is a "good day" to invest. (p. 25)
Case study: how Maya, 26, kept putting $400/month into an S&P 500 index fund straight through a 14%-in-six-weeks drop, and why that was the whole game. (p. 26)
The single rule that makes speculation safe: it's sizing, not activity. Capped at 5-10%, even a bet that goes to zero can't wreck you. (p. 27)
The one non-negotiable rule, and why it's the cap, not the calendar. (p. 28)
Crypto, options, angel deals, real-estate flips, a friend's business, with the blunt warning that every one of them can go to zero, and why that's perfectly fine here. (p. 29)
Case study: how Sarah put $8,000 into a friend's restaurant and slept fine, because it was capped and labelled. (p. 30)
The decision tree that ends the debate for good, sorted by interest rate, so you always know what to attack first. (p. 33)
The one exception that overrides everything else, hint: it's the free money most people leave sitting on the table. (p. 33)
The worksheet that lays every debt you have in priority order on a single page. (p. 34)
Why your brain panic-sells at the worst possible moment, and the “Do Nothing” portfolio that quietly beats it. (p. 36)
The pre-commitment worksheet: decide today, in writing, exactly what you’ll do when the market falls, so fear never gets a vote. (p. 36)
The kid-sized bucket system by age band, from three jars at 5-8, to a real savings account at 9-12, to a custodial brokerage with one index fund at 13-16. (p. 40)
57% of parents regret not having more money conversations. Here's exactly how to start one. (p. 40)
Why most owners don't actually have an income, they have a business bank account, and the buffer (tax reserve, operating reserve, owner-pay account) that sits underneath your personal four buckets. (p. 41)
The formula for your Owner Pay Number, and why you always round down. (p. 44-45)
Case studies: Dana, whose design-studio revenue swings from $9,000 to $22,000 a month, landing on a steady $6,500 fixed owner pay (p. 46); and Marcus, who ran a $1.4M business exit straight through the four buckets because he'd already built the discipline (p. 47).
The master allocation table, the exact percentage for each bucket based on how many years until retirement, from 25+ years out all the way into retirement. (p. 51)
Three fully worked examples, from Maya's $6,300 to Robert & Sarah's $920,000. (p. 52-54)
A 6-question quiz that tells you your single next step. (p. 55)
The 4-Phase Implementation Checklist, each phase deliberately scoped to fit inside 20 minutes. (p. 58)
A 16-term plain-English glossary (p. 68), a full FAQ appendix (p. 63), the complete Sources & Notes page (p. 70), and notebook pages.
The closing idea most money books miss entirely: the 3 M's, Make, Manage, Multiply, and the missing fourth that changes everything: Protect. (p. 77)
Every reason you've stayed stuck. And the exact page that answers it.
Forty-eight worries. Forty-eight page numbers.
What you've been thinking | Where the book answers it | Page |
"I'm more afraid of running out of money than I am of dying." | The Introduction, the exact fear this system was built to end | p. 6 |
"I just want to stop feeling anxious about money." | "It replaces anxiety with action," the one question that ends the spiral | p. 7 |
"Money stress keeps me up at night." | Why the Safety Bucket exists: turning a crisis into an inconvenience | p. 10 |
"I'm afraid I'll outlive my retirement savings." | The Safety Bucket's opening premise, and the number you can calculate this week | p. 10 |
"Healthcare costs and inflation scare me more than anything." | Why this framework says 6-12 months, not the old 3-6 | p. 11 |
"Isn't holding a year of cash a waste? Isn't inflation eating it?" | Reader FAQ: the honest answer, including what you're actually trading away | p. 12 |
"I don't understand any of the terminology." | Safety vehicles in plain English: HYSA, money market fund, CD, T-bill | p. 13 |
"I don't know how much I'd actually need." | The Safety Number worksheet, about ten minutes, one bank statement | p. 14 |
"What if I can't save 6-12 months right now?" | Start with $1,000 as a mini-buffer, then build in stages | p. 15 |
"I'm saving for a house, where does that money go?" | Reader FAQ: needed within 3 years? It belongs in Safety, not the market | p. 15 |
"I have a budget, but I'm still living paycheck to paycheck." | The Income Bucket, why a budget rearranges money it can't create | p. 16 |
"I want to stop depending on one paycheck." | Building a second, quieter source of cash that doesn't ask for more hours | p. 16 |
"Do I even need this if I'm not retired?" | Reader FAQ: yes, with the reinvest switch flipped on | p. 17 |
"Isn't an annuity just the thing insurance salespeople push?" | The honest take, fees and surrender charges included | p. 18 |
"I don't know whether to stay the course or pull back when markets swing." | Volatility vs. risk, the distinction that costs people money when they miss it | p. 21 |
"Individual stocks or index funds, which do I actually buy?" | Reader FAQ, with the decision-fatigue reasoning | p. 23 |
"I want to know it's actually worth it." | The compounding table, worked out year by year (illustrative) | p. 24 |
"I don't know when to invest, what if I pick the wrong moment?" | Dollar-cost averaging, and the autopilot worksheet | p. 25 |
"Everyone says 'stay invested' how do I actually do that?" | Reader FAQ, plus Maya's story through a 14% drop | p. 26 |
"I want to bet on something exciting without wrecking everything." | The Opportunity Bucket, why the difference is sizing, not activity | p. 27 |
"Can I take an opportunity before everything else is finished?" | The one non-negotiable rule, it's the cap, not the calendar | p. 28 |
"Debt payments eat up money I'd rather be investing." | The decision tree, sorted by interest rate | p. 33 |
"Should I pause saving to attack debt faster?" | Reader FAQ: and the one exception that overrides everything | p. 33 |
"The market just dropped. What do I actually do today?" | Reader FAQ: plus the "Do Nothing" portfolio | p. 36 |
"What if I already panic-sold once and regret it?" | Reader FAQ: rebuild the process, not the track record | p. 36 |
"I don't actually know how much I'm paying in fees." | What you keep after fees over 1, 10, 20, 30 and 40 years | p. 37 |
"Where would I even look to find them?" | The four places fees hide, plus the find-your-real-fees worksheet | p. 38 |
"I want my kids to grow up smarter about money than I did." | The kid-sized bucket system, by age band | p. 40 |
"I'm still learning this myself, can I really teach it?" | Reader FAQ: learning alongside them is the model, not a disqualifier | p. 40 |
"My income is unpredictable, so none of this applies to me." | The Business Owner's Bridge, creating an income where there wasn't one | p. 41 |
"What if I have a bad month?" | Reader FAQ, that's exactly what the Operating Reserve is for | p. 48 |
"I have no idea how my money should be split." | The full allocation table, by years until you need the money | p. 51 |
"I don't know which of these to do first." | The 6-question quiz, and what your score means | p. 55–57 |
"I don't even know where to begin." | The 4-Phase Implementation Checklist, each phase fits inside 20 minutes | p. 58–62 |
"I don't have enough saved to justify paying fee-only planners for advice." | FAQ Appendix: what fee-only planners actually cost | p. 64 |
"I don't trust financial advisors or online finance influencers." | FAQ Appendix: and why you shouldn't fully trust this book either | p. 64 |
"Nobody ever taught me this in school. Am I behind?" | FAQ Appendix: starting later isn't a personal failing, it's the norm | p. 64 |
"Every time I get ahead, prices go up and I'm behind again." | FAQ Appendix: what the Growth Bucket is actually for | p. 64 |
"I compare my finances to other people's and feel behind." | FAQ Appendix: the private scoreboard that replaces the comparison | p. 64 |
"I track everything and nothing changes." | FAQ Appendix: tracking shows where money went; buckets decide where it goes | p. 65 |
"I feel like my net worth says something about my worth as a person." | FAQ Appendix: separating the math from the meaning | p. 65 |
"I don't have anyone to actually talk to about money." | FAQ Appendix: plus the "share your plan" step in Phase 4 | p. 65 |
"How do I know my money will actually last?" | FAQ Appendix: the Monte Carlo checkup, and free places to run one | p. 66 |
"I don't want a book about not running out of money. I want to make more." | FAQ Appendix: answered head-on, not dodged | p. 66 |
"Where do real estate, gold, crypto and my business fit?" | FAQ Appendix: no asset is safe or risky by nature | p. 67 |
"What about insurance, wills and trusts?" | FAQ Appendix: what this book deliberately left out, and why | p. 67 |
"I don't understand a lot of the basic terminology." | The full 16-term plain-English glossary | p. 68–69 |
"How do I know these statistics are real?" | Sources & Notes: every study named, dated and linked | p. 70–74 |
This book was built from problems first, not chapters first.
That's not a coincidence, and it isn't clever writing. It's what happens when the research comes before the book instead of after it.
Instant digital delivery • 10 implementation tools included
OR
The book tells you what to do.
These Six tools are why you'll actually do it.
Reading and doing are different activities. This is the bridge.
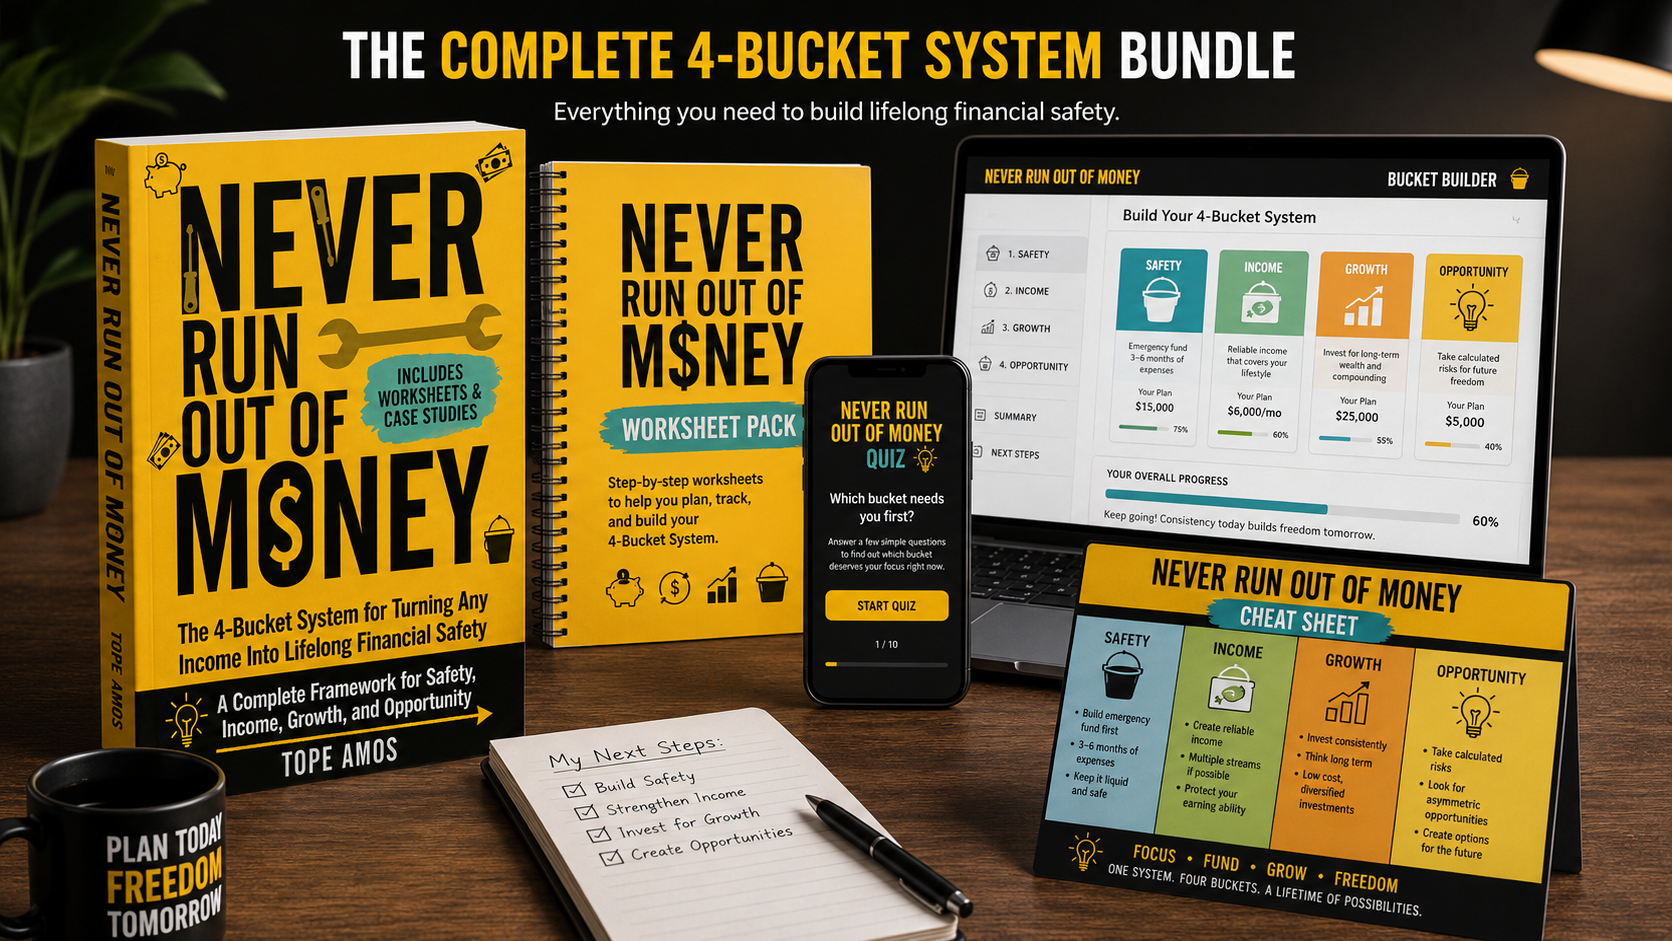
One-Page Money Map
The Chapter 10 master allocation table on one printable page. Stick it inside a cupboard door and you never have to reread the chapter.
10-Minute Money Date Checklist
A simple monthly review ritual. Ten minutes, once a month, in a fixed order, so the system keeps running after the excitement wears off.
Account-Name Translator
The same four buckets, named the way your country names them.
US - 401(k) / IRA
Canada - RRSP / TFSA
UK - ISA / workplace pension
Diaspora - how the buckets map when your money sits in more than one country
Everything you get today | |
|---|---|
Never Run Out of Money - 81 pages | $19 |
The Bucket 6-Worksheet Pack | $27 |
"Which Bucket Needs You First?" Quiz | $19 |
One-Page Allocation Cheat Sheet | $15 |
10-Minute Money Date Checklist | $22 |
Account-Name Translator — US / Canada / UK / Diaspora | $9 |
Total value | $111 |
$111
$19
Instant digital delivery • 10 implementation tools included
OR
What is lifelong financial calm actually worth?
A single hour with a financial advisor can cost more than this entire book. And here's the trap most people fall into: in GOBankingRates' 2025 survey, 40% of men and 29% of women said they'd need $100,000 or more saved before they'd even pay for professional financial advice. Which means most people get no guidance at all for years, during the exact window when compounding matters most.
Meanwhile, as you'll see in Chapter 7, a "small" 1% fee can quietly cost you around a quarter of your lifetime growth.
This book costs less than a takeout dinner for two. | |
|---|---|
$400 | One hour with a financial advisor |
$297 | A comparable online course |
$111 | The Complete System, valued piece by piece |
$19 Your price today
Instant digital delivery • 10 implementation tools included
OR
The 7-Point Guarantee
You didn't buy another book to read. You bought a system to use.
By the time you complete the 4-Bucket System, you should be able to check all 7 boxes:
☐ Calculate your Safety target
Know the amount you want set aside to protect your financial life from unexpected expenses and income disruptions.
☐ Set your Income target
Know how much recurring income you want your money to eventually produce and the capital required under your chosen assumptions.
☐ Define your Growth goal
Know what your long-term Growth money is for, your time horizon, and what you're investing toward.
☐ Establish your Opportunity fund
Have money deliberately set aside for opportunities without automatically taking it from Safety or Growth.
☐ Assign your existing money
Know which bucket your current savings, investments, and other financial assets belong to—and why.
☐ Know where your next dollar goes
Have a repeatable decision process for determining which bucket should receive your next dollar.
☐ Complete your personal 4-Bucket Plan
Have your four targets, current balances, gaps, and next actions documented in one place.
The Guarantee
If you complete the worksheets and cannot check all 7 boxes, don't simply give up.
Send us your completed 4-Bucket worksheet to hello@topeamos.com and we'll help you identify the missing piece and point you to the specific lesson or tool you need to complete your plan.
Because the goal isn't for you to finish the book.
The goal is for you to finish with a system.
This guarantee covers completion and understanding of the 4-Bucket framework. It does not guarantee investment returns, income levels, market performance, or any particular financial outcome.
The questions people actually ask
That's exactly who this was written for. The book opens with a 6-question quiz that points you to your single next step, and a checklist where each phase fits inside 20 minutes. You are never asked to do everything at once.
This book doesn't ask for blind faith. Every statistic is named and dated on the Sources & Notes page, and every worksheet is built so you confirm the conclusion with your own numbers. Believe the math, not the author.
Chapter 2 reframes this as an income-timing problem, not a willpower failure, and it starts with automatic transfers you can set as small as you need. Alex started at $450/month; you can start far smaller.
Then a $19 book may be the best-value financial guidance you'll get for years. No minimums, no AUM fee, no upsell to a product you didn't ask for. It's a system you run yourself, which is why it costs $19 and not $400 an hour.
No. This is financial education. It teaches you a repeatable system for making your own decisions, but it doesn't know your tax position, your dependents or your health, and it's honest about when to bring in a licensed professional.
There's a path for each. Chapter 9 handles irregular business income specifically; the rest of the system works for salaried, hourly, and mixed income alike.
Instant digital download (PDF), straight after checkout. The book, all seven tools.
No. The book itself has worksheets inside that you can fill out with a pen. But the digital bonus pack (fillable PDF worksheets, Quiz, cheat sheet, checklist, and account translator) is exclusive to customers who purchase the digital version directly from this website.
The print book = worksheets in the book.
The digital version = worksheets in the book + the full bonus pack.
If you want the bonuses, buy the digital version here. If you just want the physical book, grab it on Amazon.
Why now, honestly?
There's no countdown clock.
There won't be a fake one.
The real urgency is arithmetic. Every month a dollar sits idle in the wrong bucket is a month it isn't protecting you or growing for you.
The best time to give your money a job was years ago. The second-best time is tonight.
Stop doing money math at 2 a.m.
Give every dollar a job.
Instant digital delivery • 10 implementation tools included
OR
P.S - Remember the number that started this page: 64% of Americans now fear running out of money more than they fear dying. That fear doesn't disappear by earning more or budgeting harder. Plenty of high earners feel it too. It disappears when every dollar you own knows its job. That is the entire promise of the four buckets. |
P.P.S - If you'd rather start smaller, get the book for $19 and run the Safety Number worksheet tonight. |
This website and the book Never Run Out of Money are for general educational and informational purposes only and do not constitute personalized financial, investment, tax, or legal advice. The information is general and impersonal in nature and is not tailored to the investment needs, objectives, risk tolerance, or financial situation of any specific person. You should not rely on this information as a substitute for professional advice. All investing involves risk, including the possible loss of principal. Past performance is not a guarantee of future results. Any case studies or examples are for illustrative purposes only. You are solely responsible for your financial decisions. If you need personalized advice, you should consult a qualified licensed professional
Due to the digital nature of the products sold on this website, all sales of ebooks and digital downloads are final. We do not offer refunds or exchanges. However, we are committed to your satisfaction. If you have any issues with your purchase or find the material confusing, please reach out to us at hello@topeamos.com, and we will do our best to help you get value from the book.
Last Updated: August 2026
Tope Amos ("we," "our," or "I") operates the Never Run Out of Money website and sells digital products. This Privacy Policy explains how we collect, use, and protect your personal information when you visit our website or purchase our products.
1. Information We Collect
We collect the following types of information:
Information You Provide Directly:
Contact Information: Your name and email address when you sign up for our newsletter, purchase a product, or contact us.
Order Information: Billing and shipping details when you make a purchase (processed securely by our payment processor).
Communications: Any information you provide when you email us at hello@topeamos.com.
Information Collected Automatically:
Usage Data: Information about how you interact with our website (pages visited, time spent, links clicked).
Device Information: Your IP address, browser type, and operating system.
Cookies: Small data files stored on your device that help us improve your experience. You can disable cookies in your browser settings.
2. How We Use Your Information
We use your information to:
Process and deliver your purchases
Send you order confirmations and updates
Respond to your questions and support requests
Send you occasional emails about updates, new products, or promotions (you can unsubscribe at any time)
Improve our website and understand how visitors use it
Comply with legal obligations
3. Third-Party Sharing
We do not sell, rent, or trade your personal information to third parties. However, we may share your information with trusted service providers who help us operate our business:
Payment Processors: To process your payments securely (e.g., Stripe, PayPal).
Email Service Providers: To send you emails and manage our mailing list (e.g., Mailerlite).
Website Hosting & Analytics: To host our website and understand visitor behavior (e.g., Google Analytics).
These providers only have access to the information needed to perform their specific functions and are required to keep your information confidential.
4. Data Security
We take reasonable measures to protect your personal information from unauthorized access, disclosure, alteration, or destruction. However, no method of transmission over the internet is 100% secure, and we cannot guarantee absolute security.
5. Your Rights
Depending on your location, you may have the following rights regarding your personal information:
Access: Request a copy of the information we hold about you.
Correction: Request that we correct inaccurate information.
Deletion: Request that we delete your information (subject to legal requirements).
Opt-Out: Unsubscribe from our marketing emails by clicking the "unsubscribe" link in any email.
To exercise any of these rights, email us at hello@topeamos.com.
6. Cookies
Our website uses cookies to enhance your experience. Cookies are small text files stored on your device. You can choose to disable cookies in your browser settings, but this may affect your experience on our site.
7. Children's Privacy
Our website and products are not intended for children under 13, and we do not knowingly collect personal information from children under 13.
8. Changes to This Policy
We may update this Privacy Policy from time to time. Any changes will be posted on this page with an updated "Last Updated" date.
9. Contact Us
If you have questions about this Privacy Policy, please contact us at:
©2026 All rights reserved.
Terms of Service for Never Run Out of Money
Last Updated: August 2026
Welcome to Never Run Out of Money. By using this website and purchasing our products, you agree to the following Terms of Service. Please read them carefully.
1. Acceptance of Terms
By accessing or using this website (including purchasing any products), you agree to be bound by these Terms of Service. If you do not agree to these terms, please do not use this website.
2. Products and Purchases
Digital Products:
All products sold on this website are digital downloads (e-books in PDF/ePub format).
Due to the digital nature of these products, all sales are final. We do not offer refunds or exchanges.
However, we are committed to your satisfaction. If you have questions or need help, please contact us at hello@topeamos.com.
Pricing:
Prices are listed in USD and are subject to change without notice.
We reserve the right to modify or discontinue any product at any time.
Delivery:
Digital products are delivered instantly via download link after purchase.
You will also receive a confirmation email with download instructions.
Print Editions:
If a print edition is offered, it will be shipped to the address you provide during checkout.
Shipping costs and delivery times will be specified at checkout.
3. License and Usage
When you purchase our digital product, you are granted a limited, non-exclusive, non-transferable license to use the product for your personal, non-commercial use.
You may NOT:
Share, distribute, or resell the product to others
Reproduce or copy the product for commercial purposes
Remove any copyright or attribution notices from the product
Modify or create derivative works from the product
You MAY:
Download and store the product on your personal devices
Print a copy for your personal use
Use the worksheets for your personal financial planning
4. Intellectual Property
All content on this website, including text, graphics, logos, images, and the book Never Run Out of Money, is the intellectual property of Tope Amos and is protected by copyright and other intellectual property laws. You may not reproduce, distribute, or create derivative works without explicit written permission.
5. Educational Purpose and Disclaimer
This website and the book Never Run Out of Money are for educational and informational purposes only. They do not constitute personalized financial, investment, tax, or legal advice.
The information is general in nature and is not tailored to your specific financial situation.
All investing involves risk, including the possible loss of principal.
Past performance does not guarantee future results.
Any case studies, hypothetical examples, or calculations are for illustrative purposes only.
You are solely responsible for your financial decisions. If you need personalized advice, please consult a qualified licensed professional.
Limitation of Liability:
To the fullest extent permitted by law, Tope Amos shall not be liable for any direct, indirect, incidental, consequential, or punitive damages arising from your use of this website or our products, including any financial losses or decisions made based on our content.
6. User Conduct
By using this website, you agree not to:
Use the website for any unlawful purpose
Post or transmit harmful, defamatory, or offensive content
Attempt to gain unauthorized access to our systems
Interfere with the security or functionality of the website
7. Third-Party Links
Our website may contain links to third-party websites or services. We are not responsible for the content, privacy policies, or practices of third-party sites. You access them at your own risk.
8. Termination
We reserve the right to terminate your access to this website or our products if you violate these Terms of Service, engage in fraudulent activity, or misuse our products.
9. Governing Law
These Terms of Service shall be governed by and construed in accordance with the laws of [Your State/Country], without regard to its conflict of law provisions.
10. Changes to These Terms
We may update these Terms of Service from time to time. Any changes will be posted on this page with an updated "Last Updated" date.
11. Contact Us
If you have questions about these Terms of Service, please contact us at:
By submitting your information, you agree to our Privacy Policy and understand that we will use your information for the primary purpose of communicating with you and marketing our products and services.
Disclaimer: The advice provided in this publication (including all related Never Run Out of Money assets such as the digital book, audiobook, worksheets, quizzes, and related materials) is general advice only. It has been prepared without taking into account your objectives, financial situation, or personal needs. Before acting on this advice, you should consider the appropriateness of the advice, having regard to your own objectives, financial situation, and personal needs. To the maximum extent permitted by law, the author and related entities and the publisher disclaim all responsibility and liability to any person, arising directly or indirectly from any person taking or not taking action based on the information provided.
This site is not a part of the Facebook™ website or Facebook™ Inc. Additionally, this site is NOT endorsed by Facebook™ in any way. FACEBOOK™ is a trademark of FACEBOOK™, Inc.
This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.
All pricing in USD. Canadian customers: GST/HST may apply based on your province of residence.
Email: hello@topeamos.com
© 2026 Tope Amos. All rights reserved.